

10 November 2026
The Bank of England raised the base interest rate by 0.25% to 4% on Thursday, its first increase since August 2023, with Consumer Price Index ("CPI") inflation at 3.5% for the year to September from 3.1% in August and the Bank expecting it to reach around 5% in the second quarter of 2027 as the energy shock feeds through. Governor Andrew Bailey said a further increase could come as early as December, with the minutes pointing the same way. Households were already under strain: the Lloyds house price index fell 1.2% in the year to October, its steepest annual fall in three years, and British Retail Consortium data showed retail footfall down 4.7% over the same period, providing an indication of consumer sentiment.
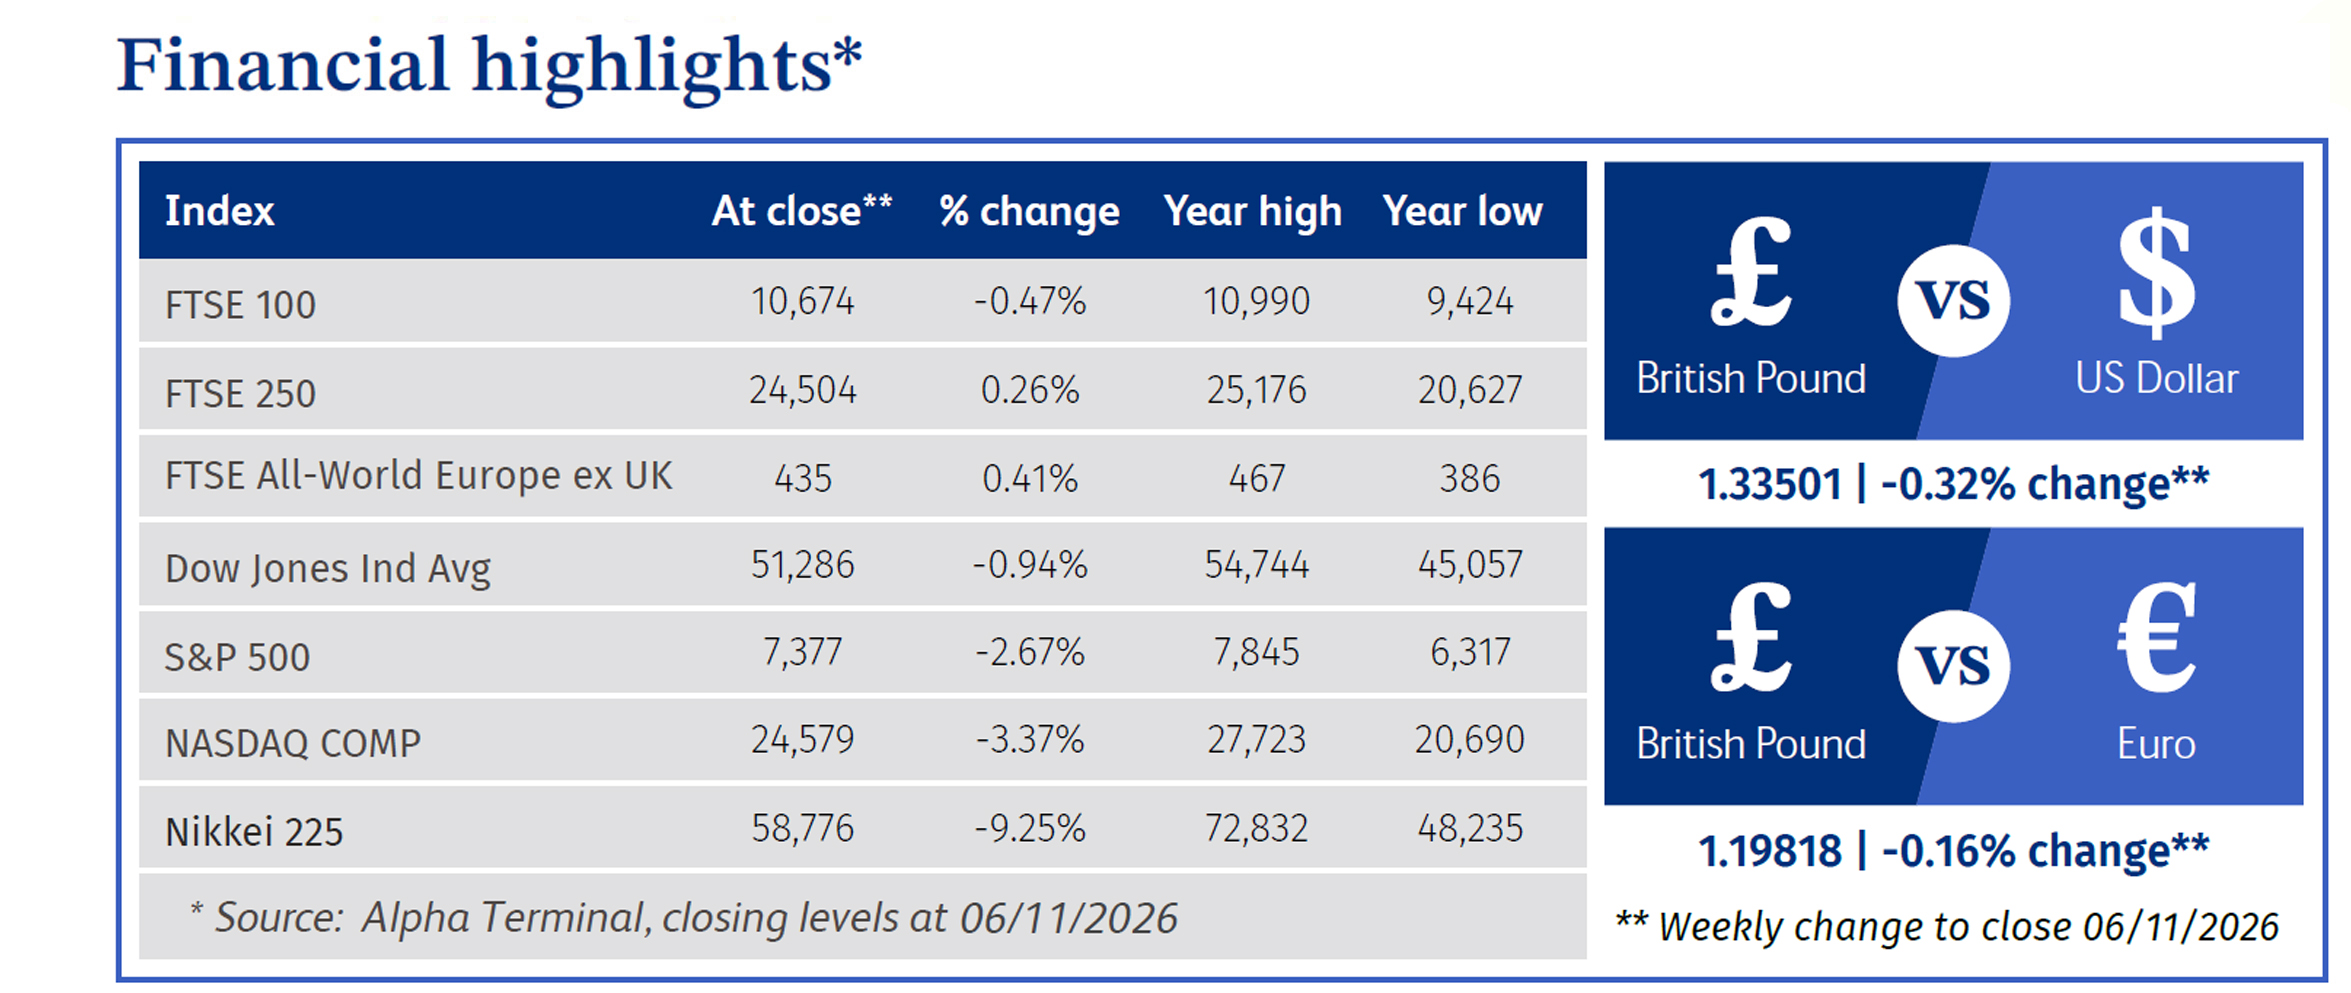
Brent Crude fell around 16% over the week to $98 a barrel as Washington signalled progress in talks with Iran and the prospect of the Strait of Hormuz reopening reduced escalation risk. In London, energy shares came under pressure, weighing on the FTSE 100, which ended lower, while the mid-cap FTSE 250 index finished slightly higher, helped by the 10-year gilt yield falling to 5.15% from 5.28%, even as the base interest rate rose. Retail results gave the market something firmer, with retailer Next lifting full-price sales 8.1% in the 13 weeks to 31 October against guidance of 5.8%.
In the US, Democrats took control of both chambers of Congress in Tuesday's midterm elections, with the market turning its eye towards potential further artificial intelligence (“AI”) oversight. Technology shares sold off heavily on Thursday, with disappointing semiconductor outlooks adding to the pressure, and both the S&P 500 and the Nasdaq Composite ended the week lower. Labour market data pointed the other way: the economy added 165,000 jobs in October, well ahead of consensus, and the unemployment rate edged down to 4.1% from 4.2%. Treasury yields still fell, the 2-year to 4.51% from 4.59% and the 10-year to 4.86% from 4.93%, on safe haven demand and a lower implied chance of fiscal expansion.
Eurozone headline inflation accelerated to 4% in October from 3.8% in September, double the European Central Bank's 2% target, driven largely by energy inflation of 20.8%. Activity was moving the other way, with the Hamburg Commercial Bank Eurozone Composite Purchasing Managers' Index ("PMI"), a survey which tracks the health of the eurozone private sector economy, falling to 51.7 in October from 53.1 in September, where 50 separates expansion from contraction. European equities still rose, as lighter exposure to AI-linked technology shares spared the region the steeper falls seen in the United States.
Japanese equities fell sharply, the Nikkei 225 entering a technical bear market more than 20% below its June record high, as concern over the outlook for AI data centre expansion hit semiconductor shares. The domestic picture was firmer, with average nominal wages rising 4.6% for the year to September and the Japan Composite PMI, published by the mobile-first digital bank au Jibun Bank, slipping marginally to 52.1 in October from 52.3 in September. The yield on the 10-year Japanese government bond fell to 2.64% from 2.77% as lower oil prices eased inflation concerns, prompting some reassessment of a Bank of Japan increase in December.
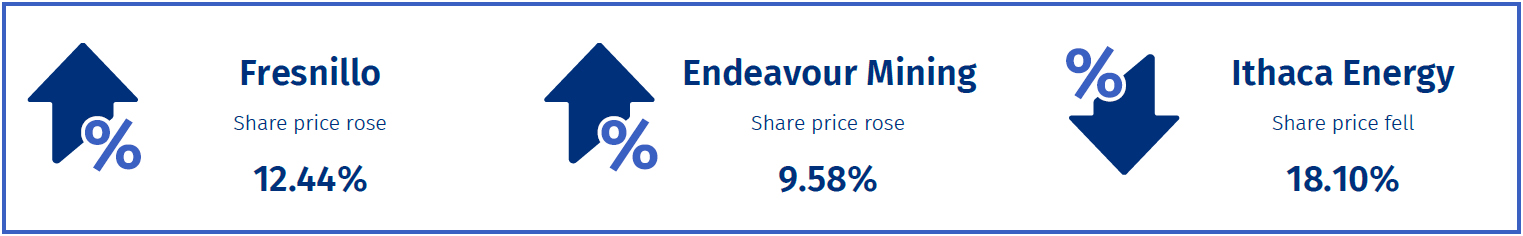
Fresnillo, a Mexico-focused precious metals mining company producing silver and gold across several major exploration districts, rose 12.44% over the week to stand at £25.13 per share following a sector-wide rally in bullion prices linked to the US midterm election outcome. Investor sentiment was lifted as market participants reassessed precious metals valuations, boosting optimism around the economics of Fresnillo's $3 billion capital expenditure pipeline. There was also a tailwind from a broader rotation into tangible assets, as sentiment toward semiconductors and mega-cap tech softened amid heightened scrutiny of AI capital spending. While higher gold and silver prices improved near-term earnings expectations, shareholders remained mindful of underlying operational headwinds, including Mexican labour costs and grade dilution, which make day-to-day mine execution the decisive factor for long-term returns.
Endeavour Mining, a gold producer operating multiple mines across Africa, gained 9.58% over the week to stand at £40.94 per share amid a sharp bullion rebound and positioning ahead of its third-quarter results. Market mood was supported by lower Treasury yields and a weaker US dollar, which spurred renewed buying interest across gold equities. Similar to Fresnillo, it coincided with investors trimming exposure to technology and semiconductor names in favour of commodities. Sentiment was further bolstered by the prospect of enhanced shareholder returns, as stronger gold prices underpin the company's multi-year dividend and buyback commitments.
Ithaca Energy, an independent oil and gas company exploring, developing and producing hydrocarbons across the UK North Sea, slid 18.10% over the week to stand at 248 pence per share as crude prices tumbled on Middle East diplomatic progress. Investor sentiment deteriorated sharply after signs that Iran might reopen the Strait of Hormuz erased crude's geopolitical risk premium. Given Ithaca's high operating leverage, its near-term cash flows and dividend capacity are closely tied to benchmark energy prices. Market confidence was further dampened by domestic fiscal headwinds, notably the Energy Earnings Levy (often referred to as the UK's oil and gas windfall tax) and policy uncertainty surrounding future North Sea licensing.
Market Commentary prepared by Walker Crips Investment Management Limited.
This publication is intended to be Walker Crips Investment Management's own commentary on markets. It is not investment research and should not be construed as an offer or solicitation to buy, sell or trade in any of the investments, sectors or asset classes mentioned. The value of any investment and the income arising from it is not guaranteed and can fall as well as rise, so that you may not get back the amount you originally invested. Past performance is not a reliable indicator of future results. Movements in exchange rates can have an adverse effect on the value, price or income of any non-sterling denominated investment. Nothing in this document constitutes advice to undertake a transaction, and if you require professional advice you should contact your financial adviser or your usual contact at Walker Crips. Walker Crips Investment Management Limited is authorised and regulated by the Financial Conduct Authority (FRN:226344) and is a member of the London Stock Exchange. Registered office: 128 Queen Victoria Street, London, EC4V 4BJ. Registered in England and Wales number 4774117.

Important Note
No news or research content is a recommendation to deal. It is important to remember that the value of investments and the income from them can go down as well as up, so you could get back less than you invest. If you have any doubts about the suitability of any investment for your circumstances, you should contact your financial advisor.

The value of investments can fall as well as rise. Investors may get back less than invested. Past performance is not a reliable indicator of future results.
The value of investments can fall as well as rise. Investors may get back less than invested.


