

27 October 2026
UK inflation accelerated to 3.5% in the year to September from 3.1% in August, its fastest pace since October 2025 and above the 3.4% consensus, driven by transport and motor fuels. Producer input price inflation reached 8.3% from 6.7% in August, with crude oil the largest contributor, pointing to cost pressure still in the pipeline. Unemployment fell to 4.7% in the three months to August from 4.9%, giving the Bank of England little reason to ease before its next base interest rate decision next month. Public sector net borrowing of £24.52 billion in September left the year-to-date figure £6 billion above the Office for Budget Responsibility forecast, ahead of the UK Budget tomorrow, 28th October.
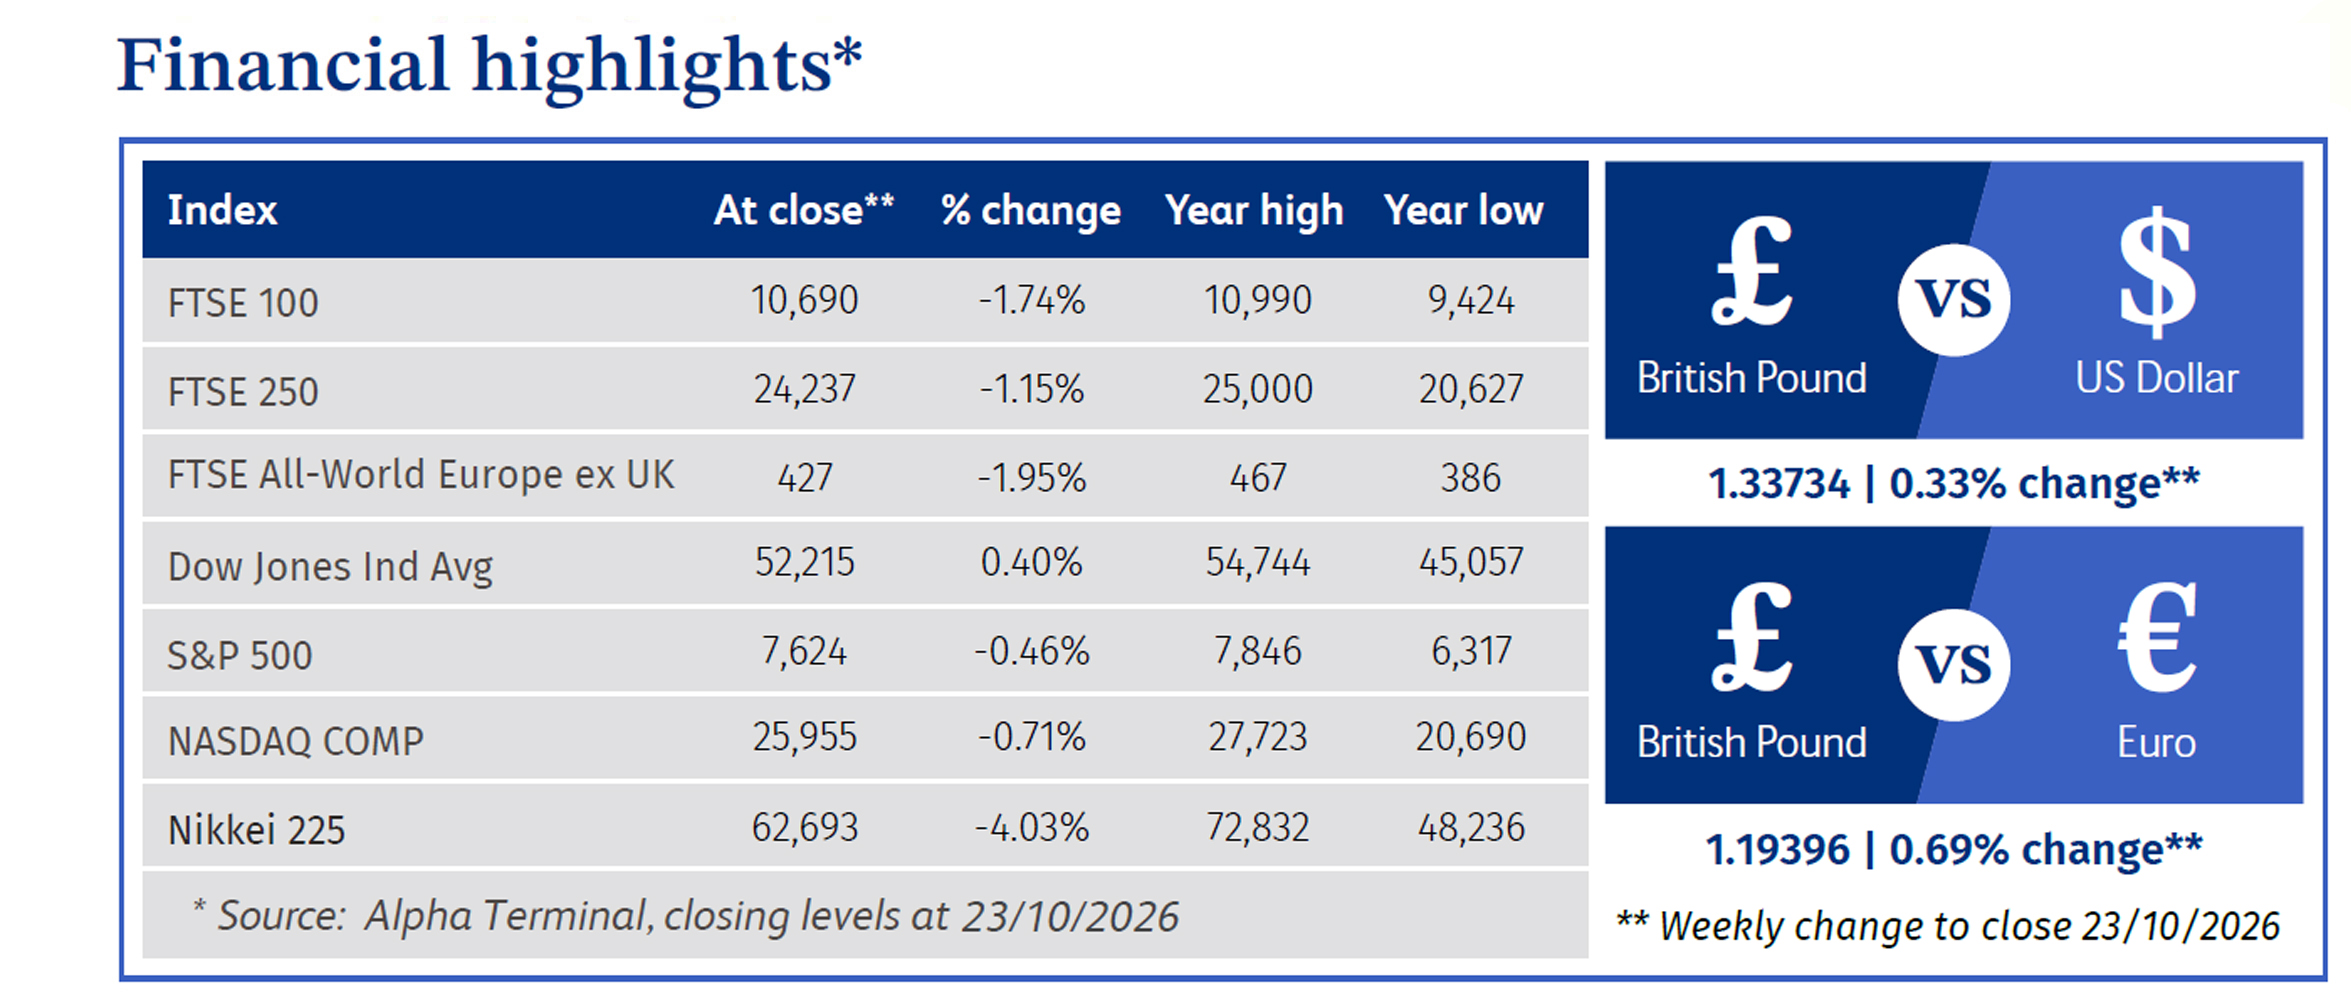
The FTSE 100 fell over the week, underperforming the smaller companies index, with energy and the global sell-off from technology setting the direction. Brent Crude climbed from $107.81 to $114.73 a barrel after Iranian mines halted three tankers in the Strait of Hormuz and Houthi attacks struck a Saudi airport and the Shaybah oil field, supporting oil and gas producers. The UK Government approved production at the North Sea Jackdaw gas field, expected to raise domestic gas production by about 6%, added to that support. Banks provided little lift, as Barclays missed consensus estimates with a £2.32 billion pre-tax profit, despite a 12% year-on-year increase.
The same oil move fed into US inflation expectations, with the University of Michigan's final October survey showing household expectations for the year ahead at 4.7% and for the longer run at 3.5%. Housing weakened, pending home sales falling 7.3% in September to their lowest since the series began in 2001. Scrutiny of artificial intelligence ("AI") capital spending and its financing weighed on the largest technology shares while value and smaller companies gained, leaving the Dow Jones Industrial Average higher and the S&P 500 and Nasdaq Composite lower. The 10-year Treasury yield fell to 5% from 5.08% and the 2-year yield to 4.68%, ahead of the Federal Reserve decision on 28th October.
European equities fell as cost-of-living protests in France turned into rioting and looting, with more than 400,000 demonstrating and close to 1,000 arrests. The yield on French 10-year government bonds rose above 5%, the widest spread over German bunds of the same maturity since 2012, and credit rating agency Moody's cut its outlook on France's Aa3 rating to negative. The German 10-year bund yield fell to 3.34% from 3.42% as investors sought safety. The European Central Bank's consumer survey showed households expecting prices to rise 3.1% over the coming 12 months, up from 3%, ahead of its rate decision on 29th October.
Japanese equities fell furthest as the reassessment of AI spending hit semiconductor shares across Asia. Core consumer prices, excluding fresh food, rose 2.1% in the year to September, the first reading above the Bank of Japan's 2% target since December 2025, strengthening the case for further rate increases, although it is reported to favour holding rates at its next policy meeting on 30th October. The 10-year Japanese government bond yield fell to 2.8% from 2.92%, with record demand at a 20-year auction. China's Gross Domestic Product ("GDP") grew 4.5% in the third quarter, above the 4.4% forecast, and the People's Bank of China left its loan prime rates unchanged.
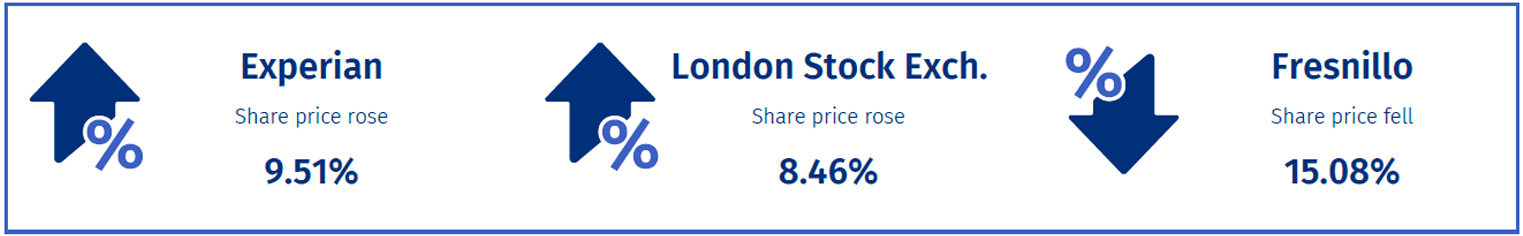
Experian, a global credit bureau that provides decision-making software and consumer credit management services, rose 9.51% over the week to stand at £31.80 per share after hotter-than-expected UK inflation sparked a market rotation into defensive, data-driven equities. As higher interest rates increase the need for lender risk monitoring and fraud prevention, investors reassessed the resilience of Experian’s subscription model. This sustained buying interest helped the firm outperform the wider market, shaking off earlier sector-wide fears regarding artificial intelligence disruption. Furthermore, the group's geographical diversification across the US and Latin America reassured shareholders that localised macroeconomic headwinds could be comfortably absorbed by its broader global operations.
London Stock Exchange Group, a global financial markets infrastructure company which provides critical data, analytics and risk intelligence services, saw its shares climb 8.46% over the week to stand at £95.10 per share after the company upgraded its full-year revenue guidance following a surge in trading activity. Higher interest rates drove a 14.4% jump in fixed income and derivatives revenue. Market sentiment was further boosted by its $3.5 billion acquisition of private credit intelligence provider Octus, expanding its highly valued subscription data business which grew 6.6%. This strategic move deepens core recurring revenues, offering investors a reliable structural cushion against any future cyclical downturns in trading volumes.
Fresnillo, a UK-listed precious metals mining company operating silver and gold mines across Mexico, saw its shares plunge 15.08% over the week to stand at £23.09 per share after reporting a sharp year-on-year drop in third quarter production. Quarterly silver output fell 12% to 10.3 million ounces, while gold dropped 11% to 135,053 ounces, driven by lower ore grades at key assets including Juanicipio and Herradura. Although the miner maintained its 2026 guidance, the declining production volumes weighed heavily on investor confidence. Markets consequently began pricing in potential risks of future operational downgrades, reflecting lingering concerns that persistent ore grade challenges could ultimately squeeze underlying margins.
Market Commentary prepared by Walker Crips Investment Management Limited.
This publication is intended to be Walker Crips Investment Management's own commentary on markets. It is not investment research and should not be construed as an offer or solicitation to buy, sell or trade in any of the investments, sectors or asset classes mentioned. The value of any investment and the income arising from it is not guaranteed and can fall as well as rise, so that you may not get back the amount you originally invested. Past performance is not a reliable indicator of future results. Movements in exchange rates can have an adverse effect on the value, price or income of any non-sterling denominated investment. Nothing in this document constitutes advice to undertake a transaction, and if you require professional advice you should contact your financial adviser or your usual contact at Walker Crips. Walker Crips Investment Management Limited is authorised and regulated by the Financial Conduct Authority (FRN:226344) and is a member of the London Stock Exchange. Registered office: 128 Queen Victoria Street, London, EC4V 4BJ. Registered in England and Wales number 4774117.

Important Note
No news or research content is a recommendation to deal. It is important to remember that the value of investments and the income from them can go down as well as up, so you could get back less than you invest. If you have any doubts about the suitability of any investment for your circumstances, you should contact your financial advisor.

The value of investments can fall as well as rise. Investors may get back less than invested. Past performance is not a reliable indicator of future results.
The value of investments can fall as well as rise. Investors may get back less than invested.


